
October 27 2026 09:30
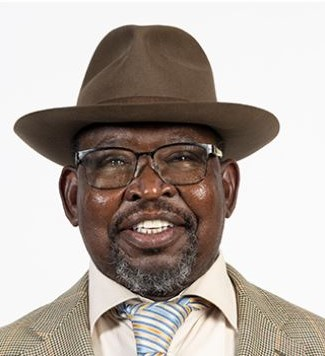
Finance Minister Enoch Godongwana’s 2026 Medium-Term Budget Policy Statement confirmed a milestone South Africa has waited more than 15 years for: government debt has stopped rising. But with growth downgraded, interest rates climbing and fuel prices at record highs, property investors, landlords and homeowners will need to look beyond the headline.
By Alistair Anderson
Enoch Godongwana tabled the Medium-Term Budget Policy Statement (MTBPS) last week, against one of the most difficult backdrops of his five years as finance minister.
The conflict involving the United States and Iran, and the disruption of oil shipments through the Strait of Hormuz, has delivered South Africa’s sharpest fuel price shock in years. In Gauteng, a litre of 95 unleaded crossed R30 this month. The economy contracted by 0.2% in the second quarter, official unemployment rose to 33.6%, and the South African Reserve Bank (SARB) has raised interest rates twice since May, taking the repo rate to 7.25% and prime to 10.75%.
The “mini-budget” was a story of two halves. On the fiscal side, the news was genuinely good: debt has peaked, the deficit is a touch narrower than expected, tax collections are running ahead of target and a legally binding fiscal anchor is on its way. On the economic side, the picture is weaker: the growth forecast has been cut by a quarter, and the Treasury is relying on a still-unproven infrastructure drive to lift it.
For the property sector, which lives and dies on interest rates, bond yields, consumer confidence and the functioning of municipalities, both halves matter.
The MTBPS is the government’s mid-year check-in. It updates February’s Budget, revises the economic and fiscal forecasts for the next three years and sets the tone for the national Budget that will follow in February 2027.
These are the key figures:
- Growth: Treasury now expects real GDP growth of 1.2% in 2026, down from the 1.6% it forecast in February. That matches the Reserve Bank’s latest projection. Global growth has also been revised down, to 3.1% from 3.3%.
- Revenue: Tax revenue for 2026/27 has been revised up by R17.1 billion, on the back of stronger corporate income tax and VAT receipts and higher commodity prices, particularly gold and platinum, which have lifted mining company profits.
- Deficit: The consolidated budget deficit is expected to narrow to 3.9% of GDP this financial year, a fraction better than the 4% projected in February.
- Debt: Gross debt peaked at 78.4% of GDP in 2025/26, below the 78.9% Treasury had expected in February, and has started to decline.
- Borrowing: The borrowing requirement for 2026/27 has risen by R54.3 billion to R443.2 billion. That sounds alarming, but most of the increase funds a domestic bond buyback programme designed to smooth out large upcoming redemptions, rather than new day-to-day spending.
The minister kept his February promise not to raise taxes in 2026, and no new tax increases were announced.
Debt has peaked, and a fiscal anchor is coming
The most important message of this MTBPS is that South Africa’s debt ratio has turned. Since the global financial crisis, the country’s debt-to-GDP ratio rose almost every year, driven by weak growth, bailouts of state-owned companies, a fast-growing public wage bill, the pandemic and the damage of the state capture years. Debt-service costs now swallow roughly one rand in every five that the Treasury collects.
Godongwana told Parliament that debt stabilised in 2025/26, as Treasury had long promised, and is now falling as a share of the economy. That matters because every rand spent on interest is a rand not spent on roads, water, policing or housing, and because a falling debt ratio lowers the risk premium investors demand to lend to South Africa.
To lock in those gains, the government released draft fiscal anchor legislation for public comment this month and expects to table it in Parliament next year. Treasury has previously signalled that it favours a principles-based anchor rather than a rigid numerical debt ceiling: a framework that commits future governments to sustainable deficits and debt, much as the inflation target constrains the Reserve Bank. The MTBPS also proposes a new set of fiscal guardrails intended to strengthen budget discipline and accountability.
Bond markets liked what they heard. South African government bonds rallied after the speech as Treasury cut its weekly bond issuance, with one analyst describing it as a bond-friendly statement that the ratings agencies should receive well.
That last point is important. All three major agencies took positive action on South Africa earlier this year. S&P upgraded the country in November 2025 and Fitch lifted its rating to BB in June. Moody’s and S&P are due to review the sovereign again in late November, with Fitch following in December. A further upgrade would bring South Africa a step closer to investment grade and could pull more foreign money back into local bonds and listed equities, including property stocks.
Fuel levy relief: R10bn at the pumps
The mini-budget’s most visible intervention for households is another round of fuel levy relief, worth R10 billion. The general fuel levy will be cut as follows:
- 4 November to 1 December 2026: R3 a litre on diesel and R1.50 a litre on petrol.
- 1 December 2026 to 5 January 2027: R1.50 a litre on diesel and R1 a litre on petrol.
This follows the temporary relief between April and June, which cost the fiscus about R17 billion. Godongwana argued that the government can afford to step in again precisely because it has rebuilt its fiscal buffers, and that the relief is temporary and designed not to undermine the consolidation path.
For the property sector, the heavier cut on diesel is significant. Diesel prices feed directly into logistics, construction, agriculture and backup power costs, and through them into the inflation basket. Any easing in fuel-driven inflation strengthens the case for the Reserve Bank to stop raising rates sooner. The relief is short-lived, though, and runs out in early January, just as many households face back-to-school costs.
Where the money is allocated
Social spending continues to dominate the budget, accounting for about 60% of non-interest expenditure. Among the new allocations:
- R1.6 billion over the medium term for child nutrition, focused on maternal care and the first 1,000 days of a child’s life.
- R810 million to recapitalise the South African Police Service vehicle fleet, and R823 million for military deployments against gang violence and illegal mining.
- An additional R3.5 billion for municipalities over the medium term to roll out smart meters.
The smart meter allocation deserves more attention from property owners than it will probably get. Inaccurate municipal billing is one of the most persistent frustrations for landlords, body corporates and commercial property managers. Electricity distribution losses also undermine municipal finances, which in turn undermines the maintenance of the roads, water networks and substations that property values depend on. Better metering will not fix municipal dysfunction on its own, but it targets one of its root causes.
The bigger structural theme is infrastructure. Treasury says it is shifting the composition of spending away from consumption and towards investment. The Infrastructure Finance and Implementation Support Agency (IFISA), announced in February, began operating on 1 April, bringing together Treasury’s public-private partnership, project appraisal and infrastructure fund capacity. Alongside the Budget Facility for Infrastructure, it is meant to fix the project preparation and procurement weaknesses that have left public infrastructure budgets underspent for years. Government says its infrastructure reforms have unlocked projects worth more than R207bn.
Godongwana summed up the approach as an effort to “build faster, maintain better and attract private investment”. In February, Treasury put public-sector infrastructure spending at R1.07trn over the medium term.
If delivery matches the rhetoric, the beneficiaries in property are clear: industrial and logistics landlords near upgraded ports, rail and road corridors; developers in nodes that get new bulk water and electricity capacity; and the construction sector more broadly. The caveat is that South Africa’s record of converting infrastructure budgets into completed projects has been poor. The Auditor-General has found municipal infrastructure projects running, on average, almost two years late.
The interest rate question
For most property owners, the most important number is not in the MTBPS at all. It is the repo rate.
After a cutting cycle that took prime down to 10.25%, the Reserve Bank changed course this year as the oil shock pushed up inflation. It raised rates by 25 basis points in May, held in July, and raised them again, unanimously, on 23 September, taking the repo rate to 7.25% and prime to 10.75%. Governor Lesetja Kganyago has warned that headline inflation could rise above 5% in the final months of 2026, before falling back towards the new 3% target by the end of 2027. The SARB’s own projections show rates broadly stable for the rest of the year, with cuts only later.
The mini-budget helps at the margin in two ways. First, the fuel levy relief takes some pressure off inflation over the next two months. Second, a credible fiscal framework lowers the risk premium in long-dated government bond yields. That yield is the benchmark against which listed property is priced and the base from which long-term lending rates are set, so lower yields support property valuations even when the repo rate is not moving.
But the MTBPS cannot override the oil price. If the Middle East conflict keeps fuel prices elevated, the Reserve Bank, which meets next on 19 November, may feel it has to keep rates higher for longer regardless of what Treasury does.
What it means for listed property
For South Africa’s REITs, this mini-budget is broadly supportive but not a game-changer.
The positives are on the cost-of-capital side. Debt stabilisation, a coming fiscal anchor, lower bond issuance and the prospect of further ratings upgrades all point towards a lower sovereign risk premium over time. REIT valuations are closely tied to the yield on the 10-year government bond so a sustained fall in that yield would lift listed property prices and lower the cost of refinancing debt.
The negatives are on the operating side. Growth of 1.2% is not enough to drive strong demand for office space, and a squeezed consumer facing higher fuel costs and higher bond repayments is not the best news for retail landlords. Rising interest rates also push up funding costs for REITs with floating-rate debt that is not fully hedged.
The sectors best placed are likely to be those with structural tailwinds that do not depend on GDP growth: logistics and industrial property, which stands to benefit from the infrastructure push; and well-located residential rental, where demand remains strong. Offshore exposure will also remain a useful hedge for many South African property counters.
What it means for homeowners and buyers
For homeowners, the mini-budget offers little direct relief, but it matters indirectly.
Every 25-basis-point rate hike adds to monthly bond repayments, and two hikes since May have eroded some of the affordability gains made in 2024 and 2025. The fuel levy cut helps household budgets in November and December, particularly for commuters in Gauteng and other inland provinces. Over a longer horizon, a government that is no longer borrowing ever-larger sums leaves more room for interest rates to fall once the oil shock passes, and that is ultimately what will drive the next leg of the residential recovery.
What to watch next
- Parliament: Finance committees accepted public submissions on the MTBPS until 26 October. Parliament will now process the Adjustments Appropriation Bill, the Division of Revenue Amendment Bill and the accompanying tax bills.
- Reserve Bank, 19 November: The final MPC decision of 2026 will show whether the SARB sees the fuel shock as a passing spike or a reason to keep tightening.
- Ratings reviews: Moody’s and S&P in late November, and Fitch in December.
- Fiscal anchor legislation: The final shape of the anchor bill, expected in Parliament next year.
- Budget 2027: The February Budget will show whether Treasury can keep the debt ratio falling while funding fuel relief, the public wage bill and the infrastructure programme.
This was a mini-budget that protected the hard-won gains in South Africa’s public finances. Debt has peaked, the deficit is narrowing and the government is putting a legal framework around fiscal discipline. That is good news for bond markets, for the ratings outlook and, over time, for the cost of capital that underpins every property deal in the country.
What it could not do is conjure growth. With the economy expected to expand by just 1.2% this year, unemployment above a third of the workforce and interest rates moving up rather than down, the property sector will be relying on the infrastructure programme to deliver, and on the oil price to retreat, before it feels the full benefit.
alistair@propertyflash.co.za
